HVAC Plumbing Electrical QuickBooks CleanupFor Texas owners
The practice is in Dallas. Shops across the state meet us on a video call, and the state rules that used to sit on the other pages live here.
Go to the form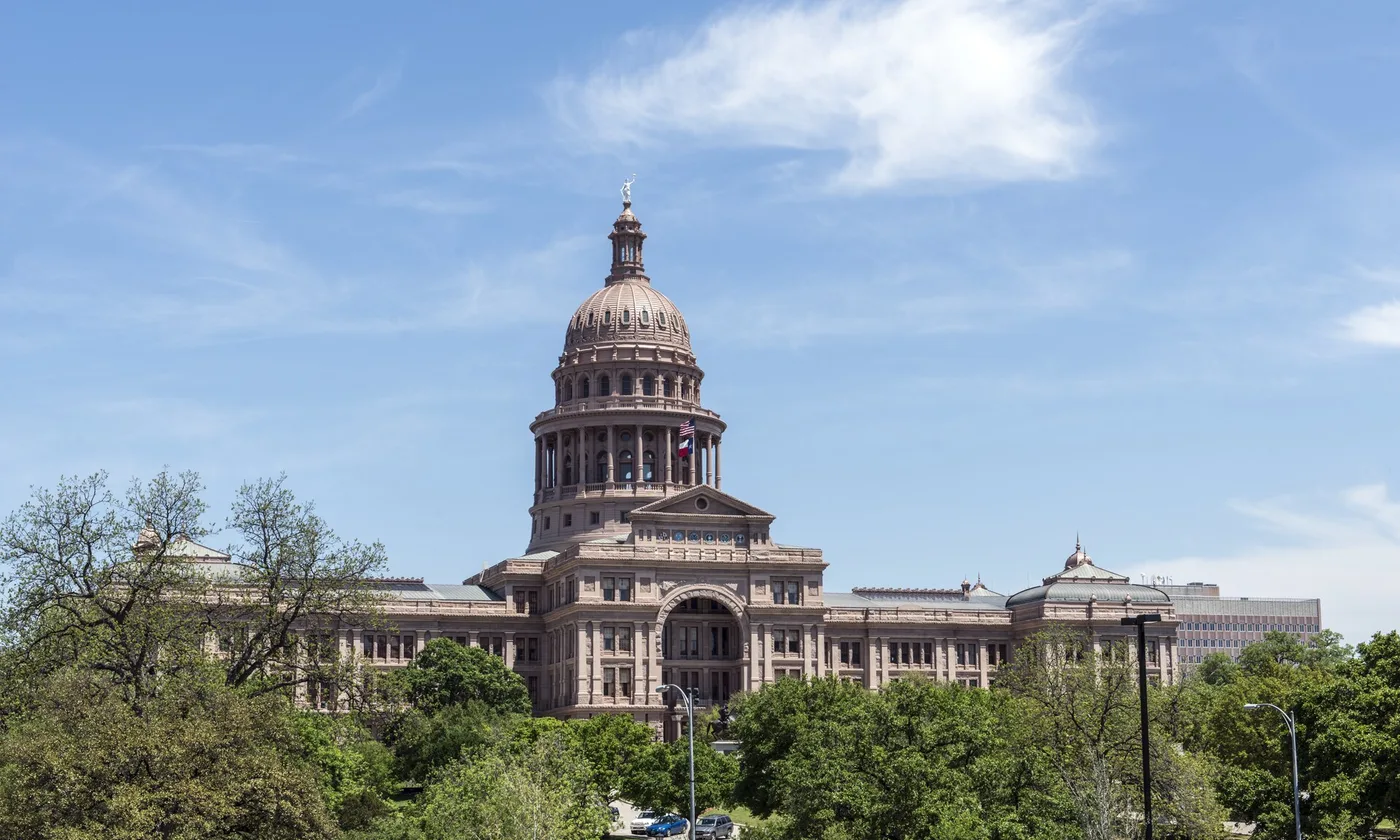
Where the work sits
The practice is in Dallas. Owners in Dallas can sit with us as neighbors. The practice is here. Everyone else in the state meets us on a video call, with the books shared and a calendar link, and the close lands on the day we agreed. We are all Texans. A reader in another city is still part of that we. We do not keep an office in Fort Worth, Houston, Austin, or San Antonio, and we do not pretend a landmark is a storefront.
People in Austin still call Lady Bird Lake Town Lake, and the habit is older than the new name. We can appreciate that water on a hot evening even from another city. This work has not taken us to that shore. Owners there get the same close on video.
Buffalo Bayou Park opened the trail from Shepherd Drive to Sabine Street, and people in Houston use it as a daily walk in the thick air. Every Texan can picture that humidity even without claiming the path. We have not walked it for this work, and we do not keep a room in Houston. Shops there sit with us over video, not in a local room of ours.
The River Walk in San Antonio runs a level below the street, and the city feels different the moment you take the stairs. That drop is one of the pleasures of the state. We have not booked a table there for this work, and we do not keep an office in San Antonio. Owners meet us remotely. Video, shared books, a calendar link, the same close.
Sundance Square in Fort Worth is a public place, and it is not an office of this practice. These pages name a phone. They do not name a street, and they do not name a mailbox. The picture on this page is the state capitol, a public domain photograph, and the capitol is not an office either. The sentences are the work.
A held breath, and a payment with no job
Every Texan knows the held breath before the Red River game at the Cotton Bowl, usually the second Saturday of October. We feel that hold when a payment has no job on it. A payment that leaves the field software with a blank job cannot close the month, because the ordinary path credits what the customer owes and debits the holding account. We stop and ask which job it belongs to before the batch posts.
Cotton Bowl Plaza at Fair Park is a wide public space. Nothing about a plaza, or about the capitol in the picture, is a promise of a result. A clean close is something we work toward. A warranty is a different paper. These pages are not that paper.
When Pumpkin Village goes up in the Pecan Grove at the Dallas Arboretum, neighbors in Dallas slow down for an afternoon. We enjoy that walk, and we still ask whether a deposit is revenue yet. The flower beds at the arboretum are a different afternoon, color without a job number, and we can enjoy them. The file does not get that luxury. Every row needs a name both sides share.
A sunken garden is a pleasant place to wait. A close is a better one. The McCasland Sunken Garden can hold an afternoon. The half hour we want is the one where a stuck payment finally names its job.
Hail week, and the item the technician can find
Spring hail over Dallas arrives when a cool front off Canada meets Gulf humidity. We read the list first, because a visit coded wrong changes the tax. Spring hail makes a busy week. Coils get replaced, and maintenance agreements get used as the invoice because that item is the one the technician can find.
Every Texan knows the week after hail, the trucks out early and the parts counter loud. We feel that week in the list. A maintenance item used for a broken unit does not just miscategorize the work. It miscategorizes the tax, and the tax is what a later letter asks about.
Upkeep is scheduled work on property that is not broken. The contractor pays tax on the items bought to do it, and the visit itself is not the taxable repair. Replacing a belt during that visit stays upkeep. Rebuilding a broken part of a nonresidential structure is the taxable repair, labor and materials together. On a nonresidential building a coil that failed is that repair. The agreement visit is not that repair.
The record that saves the argument is plain. The visits were on a schedule, and the property was not broken when the technician arrived. The unit was running. Parts used were the parts the agreement expects. If any of those sentences is false, the visit is a repair and the invoice should say so. A shop that bills every visit as a repair, because the pricebook only has one item, will collect tax it should not, or skip tax it should. We split the items before the list posts.
The short ride, and the account names
The M-Line still runs McKinney Avenue from the Arts District to West Village, and riders in Dallas know that short trip. We know it too, and we still line up account names before a file can move on its own. Riders know the little streetcar between those two ends. The trip is short and the city feels close. We know that ride. The wink is the account list. Two systems can feel just as close and still fail, if one calls an account by a name the other does not use.
Identical names are the condition for a touchless export. We line the names up at the start. We do not rename an account in one system on a Tuesday and forget the other. Close is not the same as identical. A trailing word, a plural, a number added for a department, any of those will stop a touchless export or send the amount somewhere surprising. We print both lists and read them against each other.
El Fenix has been serving Tex-Mex in downtown Dallas since 1918, and the Wednesday enchilada is the plate neighbors still plan a lunch around. That Wednesday plate is a downtown habit we share with anyone who works near that block. Then we look at a pricebook item with an empty account and wonder which report it will break. The houses on Swiss Avenue are a real street in Dallas. They were named on the old page because they are a real street, not because the restaurant is on that street. The fact we are using is the plate, and the wink is the empty account.
The chart was mapped when the file was set up. A new item, added because a technician needed it on a call, often ships with the account blank. The export fails, or worse, it posts to a default nobody chose. We would rather name the account on a quiet Wednesday than discover the default in the middle of a close. A name that matches is a small mercy on a long chart. We read down the list the way a person reads a menu, one line at a time, and we stop at the first blank. The Wednesday plate can wait until that line has an account.
Owners in Dallas can sit with us as neighbors. The work is still the list, not a claim about a trade license. Bring the pricebook export and the chart. We will mark the blanks. Accounts receivable and the holding account stay active. They are the path. A shop that turns them off to simplify a report loses the ability to close the invoice the export created.
The yards, the stock show, and money that arrived early
The Fort Worth Stockyards are a historic district, a former livestock market that still feels like the city's front porch. The stock show runs from the middle of January into early February, and the town leans into it. We can all appreciate that stretch of the year. A deposit collected in that rush is still not revenue. It sits as unearned until an invoice earns it, whether the customer paid it beside the yards or from a kitchen table.
The Stockyards can be busy. The books can still wait. Shops take deposits because parts are expensive and no one wants to order a unit for a job that might vanish. That is good sense. The mistake is dropping the deposit into revenue on the day it hits the bank. Revenue on that day overstates the month, and it strands the sales tax conversation, because the tax follows the invoice, not the day the card was swiped.
Unearned is a liability. It says we owe the customer the work, or we owe the customer the money back. When the invoice is written, the deposit moves, and only then does the revenue exist. If the invoice is a separated contract, the tax is stated on that invoice and is not netted into the revenue line. If the job is cancelled, the deposit comes back off the liability, and the revenue accounts never knew it. Deposits stay unearned until an invoice earns them. That rule does not loosen because the job is in Austin, or because the yards are loud.
Progress bills have to say what the work is. A contract that requires those bills to state labor and materials separately is a separated contract, and it behaves like one even if someone thinks of it as a lump sum. We read the contract before we pick the account. The show being in town is not a reason to skip that read.
The close does not move because January is loud. The same day, the same check of the holding account, the same question about deposits that have no invoice yet. Owners in Fort Worth get that close on a video call with the books shared. We are neighbors in the sense that this is our part of the state. We do not pretend the yards are our storefront. During the stock show the parts counter moves faster than the books, and that is fine. What is not fine is a January revenue number that includes money for work still in February. We pull those amounts back to the liability, leave a sentence that says why, and close January on what was actually earned. The yards stay loud. The month gets quiet.
The Water Gardens in Fort Worth are a set of pools and walls, water moving on purpose. A list should move on purpose too. Bring the last export, the product that received it, and one invoice that changed after it left. If a payment is stuck, bring the job it should have hit. The half hour on these state rules does not need a login. The password stays with the shop.
The Cowtown Coliseum sits in the Fort Worth Stockyards, a room built for a crowd. A disclosure should be as readable as the sign on that building. The building is not an office of this practice. The Stockyards Visitors Center tells a visitor where they are. A page should do the same job. The words are the point, and the buildings stay where they are.
The lake, and how a contract is taxed
The lake is why an older page started where it did. The contract is the part that changes the books. New construction labor is not taxable. On a lump sum contract the contractor pays tax on purchases and does not charge the customer. On a separated contract the tax is collected on the materials that go into the job. A progress bill has to say which of those the job is, or the invoice will be read as whatever the reader fears.
Residential repair labor is not taxable when the work is on a residence. Materials follow the contract. If the contract is a lump sum, the treatment of those materials is the one the publication describes for that form. If the contract separates labor and materials, the materials carry the tax and the labor does not.
A hospital, an office, a restaurant, or a retail space is nonresidential. Repair of that real property is taxable, labor and materials. A hotel, and any stay under thirty days, does not get the residential labor treatment. A shop that uses one pricebook item for all of those buildings will be wrong on most of them. We split the items to match the building.
Send the contract, or the page of it that says lump sum or separated. Say whether the building is a house or a business. Say whether the bills are progress bills, and whether a deposit came in before the work. The worry we hear most is a letter that treats every invoice as taxable. The relief is a file where each invoice names its kind of work. New construction, residential repair, nonresidential repair, or upkeep. Four labels. With the four labels written on the bill, the return can follow the invoice instead of guessing the kind of work.
Thick air, and a unit on a wall
The picture on the national page about a failed unit is a wall unit, because that is the object the tax argument is about. It is not a stand-in for the park. The park is the sentence. The unit is the work. Upkeep is scheduled and periodic, on property that is not broken. The contractor pays tax on the items bought to perform it. A belt replaced during that visit stays upkeep. A compressor that failed on a nonresidential building is a taxable repair, labor and materials.
A maintenance agreement is a schedule. The customer is paying for the visits that were planned, not for a diagnosis of a dead unit. When the pricebook has one item and the technician uses it for both, the invoice cannot tell the story. Tax gets collected on a visit that should not carry it, or skipped on a repair that should. We would rather split two items in the pricebook than defend one blended line later.
Coils work harder in that air, and breakdowns cluster. A clustered week is when the wrong item gets used, because speed feels like service. The books can still be slow. We read the week's list before it posts, mark the visits that were breakdowns, and leave the scheduled ones alone. The letter people fear is the one that treats the whole year as taxable repair. A list that separates the two is how that letter stays short. The park can stay a walk you take. The file can stay a file we read.
A level below the street, and the tax line
The drop that matters on the invoice is the one between a house and a business. Residential repair labor is not taxable. Nonresidential real property repair is taxable, labor and materials. Hospitals, offices, restaurants, and retail are nonresidential. A hotel stay under thirty days does not receive the residential labor treatment. A commercial repair billed with the residential item is the miss we see most.
A taxable repair in this state collects a state portion of 6.25 percent, and local additions stop when the combined rate reaches 8.25 percent. On a nonresidential repair the shop collects state plus local on the total charge. A building permit fee that is stated separately, and that the contractor pays for the customer, may be left out of that base. On a separated bill the tax is its own line. Folding it into revenue makes the revenue high and the liability low, and the return then has to invent a correction. We keep the line. The river can be poetic. The tax line should stay a line.
We do not rewrite a year of invoices in the field software for sport. We identify the items that are coded as residential and used on commercial jobs, and we give those items a sibling with the right account and the right tax. Going forward, the technician can pick the building. Going backward, we adjust only the months that are still open, and we name the months that are already filed before any adjustment exports.
A technician on a roof does not want a tax lecture. The item names have to be plain enough to pick under a sun. House repair, business repair, planned visit. Three names, three accounts, three tax behaviors. Once those exist, the wrong pick is a tap, and the return stops inheriting the tap. Bring one commercial invoice and one house invoice. If they used the same item, that is the first conversation.
The franchise report, and the May letter
Most entities figure the Texas franchise tax at 0.75 percent. For reports in the current window the no tax due line sits at 2,650,000 dollars of annualized total revenue. Zero tax does not always mean zero paperwork. A public information report or an owner information report can still be due.
A single member limited liability company is still a taxable entity when the federal return disregards it. That surprise shows up in May, often as a letter, and the letter feels personal even when the math is ordinary. We would rather size the report while the year is still open than explain a missed form after the letter arrives.
The Comptroller publishes the threshold and the rate. We cite that page in the conversation, and we do not invent a penalty on top of it. If the revenue is near the line, we say so. If it is far under, we still ask whether the information report is on the calendar. The Comptroller's page controls when it and this site disagree. A sentence that is wrong gets rewritten on this page, in the open. We do not owe a particular refund, a particular saving, or a particular outcome from a letter.
These state rules were read against the Comptroller pages and the Texas tax publications the sentences name. A sales tax label on an invoice is a bookkeeping choice, not a ruling. The Comptroller's publications win when they and a label disagree. We will show the label we would use. We will not promise the label survives a later fight, and we will not be the voice in that fight.
The line the statute draws
Texas draws this boundary in the Occupations Code. A return can be prepared here. An owner can be walked through how the shop runs. Statements can be written that promise an outsider nothing. All of that can happen without the license. The moment the writing promises an outsider that the figures were checked, the work belongs with people who hold the license. A reader who wants the statutory wording can open 901.451, then 901.453, then 901.456, on statutes.capitol.texas.gov, and set them beside this paragraph. A monthly figure from us does not smuggle one of those signatures inside the fee.
The draft of the limit started from the path a field file takes into the books, then each limit was held up against those publications. Software shaped an early draft. A person here read the limits before the page was allowed to stay. If a sentence is later shown to be wrong, the page itself is edited, and the phone under the page is how that edit gets requested. These terms, where they touch this state, are read under Texas law. A problem with the site or with a conversation starts with that phone number.
Bring the visit that needs a Texas label
House, business, planned visit, or a deposit that posted early. One row is enough.

You will be talking to the Steven Palmieri practice.